Last updated: September 2026. Editorial Team — researched using reporting from CNBC and Tech Insider Canada. See “Sources & Methodology” for our full source list.
Quick Answer
Semiconductor equities are currently telling two genuinely different stories depending on which specific segment of the industry you’re looking at. AI-focused chipmakers showed real resilience this week, with Coherent gaining nearly 2%, AMD up 2%, and Qualcomm advancing more than 4%, even as the broader market fell under pressure from rising Treasury yields and the Fed’s rate hike. At the same time, the traditional client CPU business both Intel and AMD depend on faces a genuine multi-quarter gap, with both companies’ next flagship desktop processors delayed to 2027, as advanced manufacturing capacity gets absorbed by AI accelerator demand willing to pay dramatically higher prices for the same limited foundry capacity.
The AI-Exposure Divergence Playing Out in Real Time
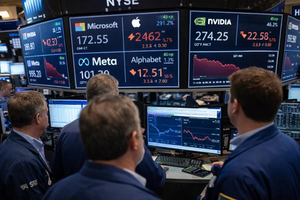
CNBC’s coverage of this week’s trading captures the specific pattern directly: losses in the S&P 500 and Nasdaq were mitigated by gains in a number of AI-connected stocks that had been under pressure in the prior session, with Coherent, AMD, and Qualcomm all posting gains even as the broader market closed lower. That divergence arrived the same week that AI industry leaders, including OpenAI’s Sam Altman and Anthropic’s Dario Amodei, publicly discussed slowing frontier AI model development over safety concerns — commentary Wall Street analysts, including Bank of America’s Benjamin Bowler, interpreted as reinforcing the case for continued AI infrastructure investment rather than a warning sign for AI-exposed equities.
Photo by ClickerHappy via Pexels
The Structural Story Underneath the Trading Pattern
What’s driving this divergence isn’t purely sentiment — there’s a genuine underlying manufacturing capacity story worth understanding. Tech Insider Canada’s analysis of semiconductor foundry economics notes broader 2026 forecasts point to industry-wide sales climbing sharply, driven overwhelmingly by AI accelerator demand rather than client CPU volume. TSMC’s 2nm wafer pricing has reportedly climbed toward $30,000 per wafer, with capacity booked out to 2028 — and when AI chip customers are willing to pay that premium for guaranteed advanced-node capacity, traditional consumer CPU production simply gets pushed further down the priority queue, a dynamic that’s now visibly showing up as Intel and AMD’s next flagship desktop platforms both slipping to 2027.
Why This Matters for Evaluating Chip-Sector Equity Exposure
This creates a genuinely important distinction for anyone evaluating semiconductor sector exposure right now: a company’s overall stock performance increasingly depends on how much of its business is exposed to AI-accelerator demand specifically, versus how much depends on traditional client CPU or general-purpose computing revenue. AMD offers a particularly useful case study of this internal divergence, since the company sits on both sides of this split simultaneously — its consumer Ryzen desktop business faces a genuine multi-quarter product gap heading into 2027, while its AI-oriented products, including the recently unveiled Threadripper Halo Station workstation with dual liquid-cooled MI350P accelerators, continue shipping on a more active cadence tied directly to AI infrastructure demand.
Qualcomm’s Notable Strength Deserves Specific Context
Qualcomm’s more than 4% gain this week is worth understanding within its own specific business context, distinct from the pure-play AI infrastructure names like AMD’s data-center-focused products. Qualcomm’s core business centers heavily on mobile and connectivity chips rather than AI training infrastructure specifically, meaning its strength this week likely reflects a somewhat different combination of factors — including broader smartphone-cycle dynamics, such as the industry-wide September device launch wave discussed in our companion coverage of the foldable smartphone shipment surge, alongside the company’s own growing AI-adjacent product positioning within mobile devices specifically.
Photo by Tara Winstead via Pexels
The Valuation Question This Divergence Raises
This split between AI-exposed and traditionally-exposed chip equities raises a genuine valuation question worth sitting with: if traditional client CPU businesses face structurally constrained near-term growth due to foundry capacity being diverted toward AI production, does that make traditionally-focused semiconductor revenue streams a smaller, less valuable piece of a diversified chipmaker’s overall business going forward? Companies like Intel and AMD, which maintain meaningful exposure to both AI infrastructure and traditional client computing, may see their overall equity valuations increasingly driven by investor perception of their AI-segment growth trajectory specifically, even as their traditional CPU business faces a genuine, multi-quarter product gap heading into 2027.
What Higher Interest Rates Mean for This Specific Sector
The semiconductor sector’s current dynamics intersect directly with this week’s broader Fed rate hike in a way worth understanding specifically. AI infrastructure investment, much of which is funded through substantial capital expenditure commitments by large technology companies, generally becomes more expensive to finance in a higher-rate environment, since the cost of capital for large, multi-year infrastructure buildouts rises alongside benchmark rates. Whether this creates any near-term headwind for the AI-infrastructure-exposed segment of the semiconductor sector specifically, even as it currently shows resilience against the broader market’s rate-driven weakness, is a genuine open question worth monitoring as the Fed’s tightening cycle potentially continues.
What This Means for Investors Evaluating Chip Stocks
- AI-exposure has become a genuine, measurable differentiator within the semiconductor sector: This week’s trading pattern illustrates real, near-term price divergence between AI-infrastructure-exposed and traditionally-exposed chip stocks, not just a theoretical distinction.
- Diversified chipmakers face a genuinely complex internal balancing act: Companies like AMD and Intel, with meaningful exposure to both segments, may see their overall stock performance increasingly driven by their AI-segment trajectory specifically, even as their traditional business faces real near-term constraints.
- Higher rates create a genuine, if currently unresolved, question for AI infrastructure financing: Whether elevated borrowing costs eventually slow the pace of AI capital expenditure commitments remains an open question worth monitoring closely.
Frequently Asked Questions
Why did semiconductor stocks diverge from the broader market this week?
AI-connected chipmakers like Coherent, AMD, and Qualcomm gained even as the broader market fell, reflecting continued investor conviction in AI infrastructure spending despite broader market pressure from rising Treasury yields and the Fed’s rate hike.
Why are Intel and AMD’s flagship CPUs delayed?
Both companies’ next flagship desktop chips have slipped to 2027, as advanced semiconductor manufacturing capacity, particularly TSMC’s 2nm production, is increasingly absorbed by higher-paying AI accelerator customers.
How does AI capital expenditure connect to this week’s Fed rate hike?
Much of the AI infrastructure buildout is financed through significant capital expenditure commitments, which generally become more expensive to finance as interest rates rise, creating a potential, still-unresolved headwind for continued AI infrastructure spending.
Should investors treat all semiconductor stocks the same way right now?
No. This week’s trading illustrates a genuine, measurable divergence between AI-infrastructure-exposed chip stocks and those more dependent on traditional client CPU or general-purpose computing revenue.
Sources & Methodology
This article draws on reporting from: CNBC’s September 15, 2026 markets coverage, including quoted commentary from Bank of America strategist Benjamin Bowler; and Tech Insider Canada’s September 2026 analysis of semiconductor foundry capacity and CPU launch delays. Figures and market data reflect data as of this article’s last-updated date and change continuously during trading hours.
This article is for informational purposes and does not constitute investment advice. It is not a recommendation to buy or sell any security mentioned.